CompaniesQBTSD-Wave QuantumWatch
QBTS earnings: an expected move of 15.8%, an actual move of 12.4%.Averages over ten of its last twelve reports. Here are all 14 reports.
D-Wave Quantum earnings reports since Nov 2022: the expected move the options priced the day before, how far the stock moved by the close and by 10:00 the next morning, and the IV crush afterwards, how far implied volatility fell. We read option prices from real quotes at 15:46 ET. Definitions on the methodology page. Two reports in that span are not shown: no option prices could be read the day before.
Next report · before the open · 2 days out
QBTS’s expected move for Tue 10 Nov
The options already price it. The number, and how rich it is against QBTS’s own history, opens free on report day, Tue 10 Nov, with an account. Subscribers read it now.
The options price an earnings move as one number. We take out the drift the stock would have had anyway, then rank what is left, the report’s own part, against QBTS’s earlier reports. Both were fixed at 15:46 ET the day before, and the history below does the same for every report.
10.0% quoted, 8.8% of it the report
The options ran two trading sessions, so the quote also carries two days of the drift QBTS has anyway: 4.8%. The two combine as squares, not sums, so 8.8 and 4.8 give 10.0. The report is 77% of that expiry’s risk.
Lower than all of its last nine
We rank only the report’s part, and only against QBTS’s own earlier reports, so a jumpy stock does not read rich for being jumpy. 8.8% is the 0th percentile: cheap for QBTS.
Moved 9.3%, past the 8.8%
−9.3% by the next close, −7.5% by 10:00 the next morning. The rank compares the price with QBTS’s past and does not forecast the move.
Inside its priced move after seven of ten
Past it: Mar 2025 +18.7%, May 2025 +51.2% and Aug 2026 −9.3%.
+51.2% after the May 2025 report
The options had priced 12.5%.
Fell after seven of the ten, by 7% to 36%
Median fall 17%, at the strike nearest the price, day before to day after. It rose after one.
Shrunk: 10.3% over the last four
From 19.5% over the six before. The report’s own part of the move, with the ordinary drift taken out.
| Report | Report’s partPriced | Rank | RealizedC2C | By 10:00 | Priced · realized · ±25% | CrushATM | As-sold | Open | ForecastPred. | Error |
|---|---|---|---|---|---|---|---|---|---|---|
| Aug 6 ’26 | ±8.8% | cheap0 | −9.3% | −7.5% | −23% | −19% | −10% | −18% | −5pt | |
| May 12 ’26 | ±9.6% | cheap0 | −7.0% | −3.5% | −16% | −12% | −9% | −15% | −1pt | |
| Feb 26 ’26 | ±11.0% | — | +2.5% | +6.9% | −21% | −21% | −17% | −25% | +4pt | |
| Nov 6 ’25 | ±11.8% | — | −8.5% | −6.5% | −18% | −18% | −13% | −20% | +3pt | |
| Aug 7 ’25 | ±14.9% | — | −2.3% | −1.7% | −36% | −35% | −23% | −33% | −3pt | |
| May 8 ’25 | ±12.5% | — | +51.2% | +23.5% | 13% | 35% | 10% | −25% | +38pt | |
| Mar 13 ’25 | ±16.4% | — | +18.7% | +10.9% | −10% | −13% | −6% | −29% | +19pt | |
| Nov 14 ’24 | — | — | +5.1% | −1.4% | −2% | −2% | −4% | — | — | |
| Aug 8 ’24 | ±30.1% | — | −1.2% | −4.0% | — | — | — | — | — | |
| May 13 ’24 | ±21.0% | — | +5.4% | +0.9% | −7% | −7% | — | — | — | |
| Mar 28 ’24 | — | — | −2.9% | −9.4% | −24% | −23% | −9% | — | — | |
| Nov 9 ’23 | ±22.2% | — | −17.4% | −0.3% | — | — | — | — | — | |
| Aug 10 ’23 | — | — | −12.4% | −3.7% | 2% | 2% | — | — | — | |
| Nov 10 ’22 | ±6.0% | — | +3.5% | — | — | — | — | — | — | |
| All · 14 | ±14.9% avg | 2 ranked | 11.6% avg abs | 6.6% avg abs | −16% median | −13% median | −9% median | −25% median | 10.4pt avg abs |
What the columns mean6 groups · 10 columns
- Report’s part
- The report’s share of what options priced at 15:46 ET the day before, taken from two or more expiries.
- ColumnsPriced
- Rank
- Where the report’s part sits among QBTS’s own earlier reports, up to twelve, from 0 to 100: 0 on Aug 6 ’26 means it was priced higher than 0 of the 9 before it. Rich and cheap mark the top and bottom of that range. It needs eight earlier reports with a 10:00 move, so the oldest rows have none.
- ColumnsRank
- Realized
- C2C is the move to the next close; By 10:00, the move to 10:00 the next morning.
- ColumnsC2CBy 10:00
- Chart
- The grey band is what the options priced, the dark mark where the stock closed, the bar where it stood at 10:00, on a ±25% scale.
- ColumnsPriced · realized · ±25%
- Crush
- How far implied volatility fell in the report’s expiry, from 15:46 ET the day before to the day after: at the new strike ATM and at the old one As-sold. Open reads it from the option’s 10:00 quotes the next morning, and is blank where there was none.
- ColumnsATMAs-soldOpen
- Forecast
- Pred. is the crush we published the day before, graded on the public record. Error is what happened minus the forecast, in points of the crush.
- ColumnsPred.Error
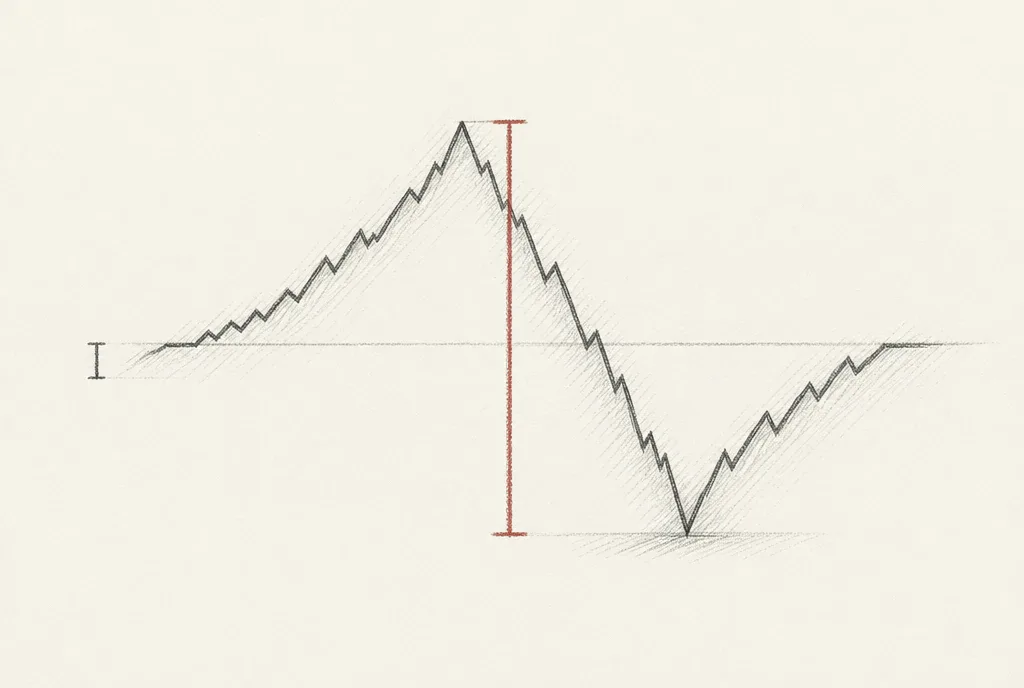 to the closein between
Closing prices miss the open
If you hold through the report you meet the open, not the close. We publish both: the move from one close to the next, and where the stock stood at 10:00 the next morning.
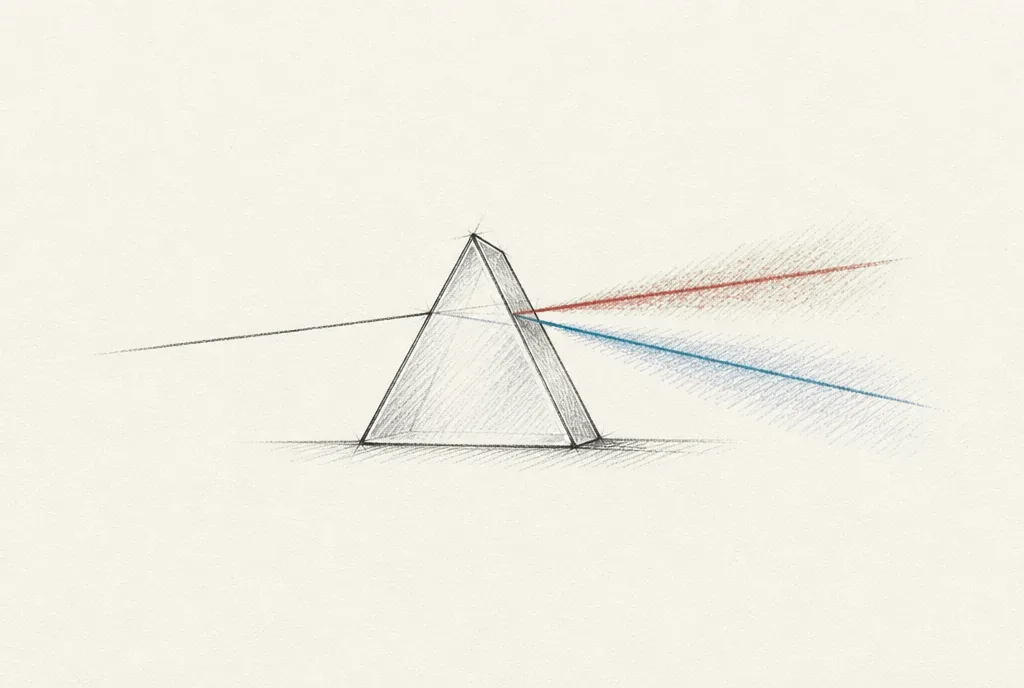 the reportordinary
Option prices cover more than the report
An expiry a week out also carries a week of ordinary movement. Comparing two expiries that both contain the report separates the two, and the report's share is the priced move.
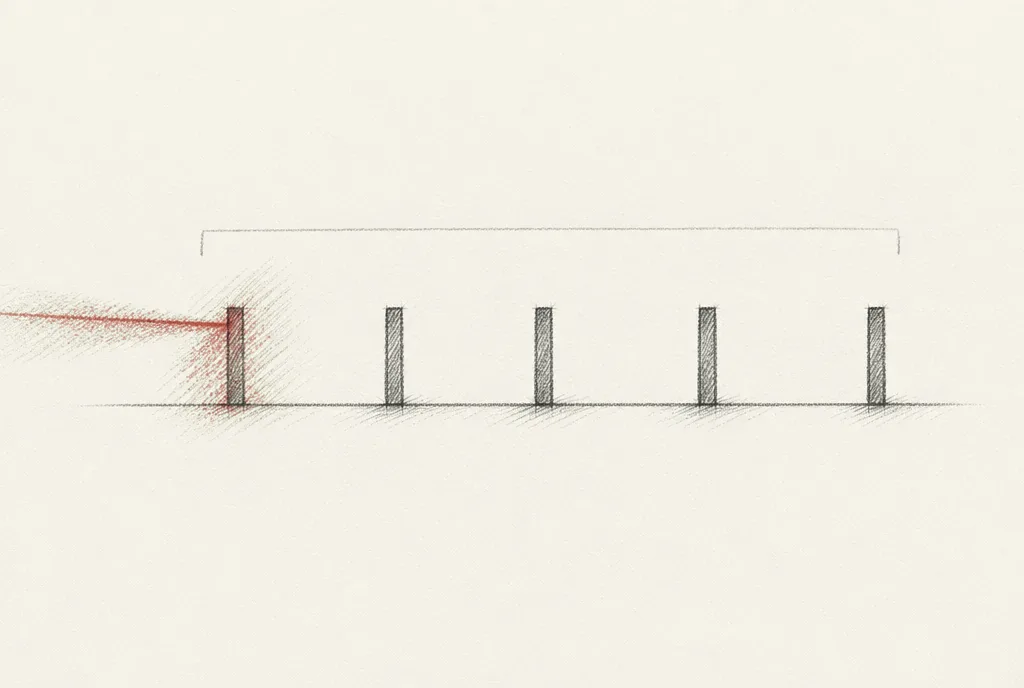 the one that movedwhat 30 days average
We measure the expiry that moved
A 30-day average mixes the expiry holding the report with expiries it never reaches, so it reads shallower than what you held. We read the expiry that holds the report, the day before and the day after, at both strikes.
One expiry contains the report. The 30-day figure is an average that also covers expiries the report never reaches. Every column below leans the same way, so the gap shows on each report, not only in the median.
Each row is one report: the band is what the options priced, the mark is where the stock closed, and the bar runs to where it stood at 10:00 the next morning. On all 10 reports with both, the close and 10:00 pointed the same way.
Where the 10:00 number is missing, the cell stays blank instead of borrowing the close, and the data-quality grid below says why. How far apart the two run differs from company to company; this window measures it for QBTS.
The split reads the report out of the gap between the two lines. The small figure under each date is how many trading sessions the expiry holding the report had left. A shorter one carries the same report over fewer days, so it reads higher without the report being priced any bigger.
Drawn for the last twelve reports, like the other figures on this page. It is history; the current curve is on the board.
Counted over the 14 reports shown. A marker on one quarter says little about the company, and one on most of them says a lot, so the count is what tells them apart.
Every marker on the reports above is counted here, one cell per report, newest first as in the history table.
’26May 12
’26Feb 26
’26Nov 6
’25Aug 7
’25May 8
’25Mar 13
’25Nov 14
’24Aug 8
’24May 13
’24Mar 28
’24Nov 9
’23Aug 10
’23Nov 10
’22reports
What each marker means23 markers · 8 withhold a number
Withheld
- no prediction7 of 14
crush_pred_unavailable - No predicted crush could be frozen for this print, so it has no entry in the scored accuracy record. Never filled in afterwards — a prediction written after the outcome is not one.
- Lands inPred.Error
- no trade at the cover4 of 14
open_crush_no_trade - The option legs did not trade at the 10:00 cover anchor, so the crush there could not be measured. It comes from the tape, not an outage, so it is permanent and counts in the published coverage ratio.
- Lands inOpen
- no T+1 ATM quote2 of 14
post_atm_unavailable - The option chain after the print was read, but the contract the crush is measured on had no two-sided quote near the money. No crush exists to measure. A property of the data, not an outage.
- Lands inEvery crush column
- overlapping event1 of 14
decomp_ambiguous - A second earnings report or a suppressing macro event falls inside the solve window, so the volatility priced there cannot be attributed to this print alone.
- Lands inPriced move
- decomposition failed1 of 14
decomp_failed - The maths that splits implied volatility into the report's own part and the ordinary part had no valid answer for this name, so its split is not published.
- Lands inPriced move
- no decomposition1 of 14
decomp_unavailable - There were not enough usable expiries, or not enough distinct ones, to separate the report's move from ordinary volatility, so its split is blank.
- Lands inPriced move
- no T+1 chain1 of 14
post_unavailable - The option chain on the session after the print has no contracts near the money within 75 days, on a date long since published. No crush exists to measure. A property of the data, not an outage.
- Lands inEvery crush column
- no 10:00 tape1 of 14
rm_intra_unavailable - The equity minute bars behind the 10:00 anchor do not exist for this session, so the anchor is blank and stays blank. It is never substituted from the opening price: a history with two different anchors mixed together is worse than a shorter one.
- Lands inBy 10:00Open
Shown, kept off the board’s sort
- wide decomposition band5 of 14
decomp_low_confidence - The decomposed implied move has a wide confidence band on this row. The number is published and kept off the board’s sort, because a sort cannot express an error bar; where its rank is shown, it is marked ≈.
- Lands inPriced move
- derived numbers unreliable4 of 14
derived_unreliable - Quotes on this name were too wide — or a 25Δ wing was missing — for the derived numbers on this row to be trusted: implied move, decomposition, crush and skew. Shown, kept off the board’s sort, and marked ≈ where its rank is shown.
- Lands inThe derived columns
- wide straddle quote4 of 14
wide_quote - The T−1 straddle’s bid-ask spread was wide relative to its own price, so every number read off that quote inherits the width. Published on purpose — the friction is real — but kept off the board’s sort, and marked ≈ where its rank is shown.
- Lands inImplied (naive)Short-straddle P&Lon the ticker page, not this one
- thin trade at the cover3 of 14
open_crush_thin_trade - Too few prints stand behind the 10:00 anchor for it to be a reliable price. The crush is shown and kept out of the rankings.
- Lands inOpen
Shown as measured
- macro event in the window13 of 14
decomp_macro_window - A scheduled macro event (a CPI print, an FOMC day) falls inside the decomposition window, so a little of the volatility attributed to the event belongs to the calendar instead.
- Lands inPriced move
- crush expiry substituted7 of 14
crush_expiry_substituted - The expiry that would have been measured was not available on both sides of the print, so a neighbouring one stood in. The crush is real; it is measured on a slightly different contract than the label implies.
- Lands inATM
- held to expiry6 of 14
cover_mark_settled - The straddle that was sold expired at one of these closes, so its price there is its settlement value: the distance from the stock to the strike. That exit pays no bid/ask spread, and it ignores the cost of being assigned stock on the in-the-money leg.
- Lands inShort-straddle P&Lon the ticker page, not this one
- skew contamination4 of 14
crush_skew_contaminated - The gap between the strike sold and where the stock ended up is large enough that the as-sold crush cannot stand in for the comparable one, so this print carries no scored open crush.
- Lands inAccuracy recordon the public record, not this one
- no re-struck cover IV4 of 14
open_crush_restruck_unavailable - The comparable at-the-money volatility could not be read at the 10:00 anchor, so only the as-sold contract is available there.
- Lands inOpen
- 30-day IV extrapolated3 of 14
iv30_extrapolated - No pair of listed expiries brackets 30 days, so the 30-day volatility was extrapolated more than a week past the nearest one rather than interpolated. A shorter reach is not flagged: it moves the number by well under one volatility point.
- Lands in30-day figureIV rankon the ticker page
- an anchor was refused2 of 14
open_crush_anchor_unreliable - At least one observation behind the 10:00 crush was rejected: a price below intrinsic, a crossed quote, or a solve that did not converge. The number here was measured from the anchors that did invert, and is scored normally.
- Lands inOpen
- cover mark above spot1 of 14
cover_mark_above_spot - A stored buy-back price exceeds the whole stock — the straddle marked above 100% of the price it is written on, which no real move in this history produces. It affects the worst-case P&L figures and nothing else.
- Lands inShort-straddle P&Lon the ticker page, not this one
- noisy IV rank1 of 14
iv_rank_noisy - This name’s quote width is large against its own 52-week volatility range, so the rank carries a read error worth noting. A true property of a quiet name, not a defect — the rank itself is computed normally.
- Lands inIV rankon the ticker page, not this one
- gapped past the wings1 of 14
open_crush_gap_otm - The stock gapped far enough that the contract sold at T−1 is no longer near the money at the cover, so the as-sold crush there is partly a move along the smile rather than a collapse in volatility.
- Lands inOpen
- next-morning price from quotes1 of 14
open_crush_restruck_quoted - The option at the 10:00 strike did not trade on both sides between 09:55 and 10:05, so the next-morning volatility was read from the midpoint of its quoted bid and ask over the same ten minutes. Used only when both sides were quoted and the quote was less than 50% wide.
- Lands inOpen
Six companies whose reports traded like QBTS’s
The closest on all three numbers at the top of each company page. It compares how the reports traded, not the businesses.
QBTSthis pagepriced 15.8% · moved 12.4%−17%
FCELFuelCell Energypriced 14.0% · moved 11.3%−17%
AMSCAmerican Superconductorpriced 14.6% · moved 15.3%−22%
OKLOOklo Inc.priced 11.1% · moved 11.3%−17%
CIFRCipher Digitalpriced 12.2% · moved 10.7%−11%
EOSEEos Energy Enterprisespriced 17.0% · moved 16.2%−24%
NBISNebius Grouppriced 11.3% · moved 12.0%−23%
- Reported · the fortnight to 5 Nov · settled, free
- Next 14 days · 523 names · symbol and date free
- ·AAONMon 9AMC—
- ·ABCLMon 9AMC—
- ·ACHRMon 9AMC—
- ·AIOTMon 9BMO—
- 11 of 523 shown · the next 14 days
The ranked columns are the board
Symbol and date are free for all 523 names. A subscription fills in the three columns held back on every locked row: the priced move, its richness against that name's own last twelve reports, and the ratio between them.
A free account adds today’s board rows and the full 14-day calendar, without these three columns.
Today's board rows and the full forward calendar are on your board.
- ·ALTGMon 9AMC—
- ·AMCXMon 9AMC—
- ·AMGMon 9BMO—
- ·AMPYMon 9AMC—
- ·AMRCMon 9AMC—
- ·ANNXMon 9BMO—
- ·APEIMon 9AMC—
| # | Name | Report | Priced move | Richness · own history | Ratio | Outcome |
|---|---|---|---|---|---|---|
| Reported · the fortnight to 5 Nov · settled, free | ||||||
| 1 | COPConocoPhillips | Nov 5BMO | 3.4% | 100 | 1.79 | inside |
| 2 | EOGEOG Resources | Nov 5AMC | 4.2% | 100 | 1.58 | inside |
| 3 | GEOGeo Group | Nov 5BMO | 9.8% | 100 | 1.31 | inside |
| 4 | GHGuardant Health | Nov 5AMC | 19.1% | 100 | 2.10 | inside |
| 5 | KTOSKratos Defense & Security Solutions | Nov 5AMC | 11.9% | 100 | 1.59 | inside |
| Next 14 days · 523 names · symbol and date free | ||||||
| · | AAON | Mon 9AMC | — | |||
| · | ABCL | Mon 9AMC | — | |||
| · | ACHR | Mon 9AMC | — | |||
| · | AIOT | Mon 9BMO | — | |||
12 of 523 shown · the next 14 days
The ranked columns are the boardSymbol and date are free for all 523 names. A subscription fills in the three columns held back on every locked row: the priced move, its richness against that name's own last twelve reports, and the ratio between them. A free account adds today’s board rows and the full 14-day calendar, without these three columns. Today's board rows and the full forward calendar are on your board. | ||||||
| · | ALTG | Mon 9AMC | — | |||
| · | AMCX | Mon 9AMC | — | |||
| · | AMG | Mon 9BMO | — | |||
| · | AMPY | Mon 9AMC | — | |||
| · | AMRC | Mon 9AMC | — | |||
| · | ANNX | Mon 9BMO | — | |||
| · | APEI | Mon 9AMC | — | |||
| · | APPS | Mon 9AMC | — | |||
How to read this page
- History table
- Its columns are explained right under it: What the columns mean ↑
- Coverage
- QBTS’s 14 reports. The board rows are the fortnight’s five richest settled reports, then the first of the next 523 names.
- Ratio
- The priced move over the name’s typical actual move.
- Markers
- Notes on a report’s data, counted in the data-quality grid with what each one touches.
A number looks wrong? Tell us what you expected and we’ll check it.Report a data issue
History is a record, not a forecast. Derived values only; no option prices are shown. Nothing here is investment advice.