Earnings recap
Implied vs actual earnings moves: Oct 26–30, 2026
October 26 to 30: our implied volatility forecast landed within 5 points on 61 of 101 reports and beat the simple guess on 72, in a hard week for sellers.
The week of October 26 had 757 earnings reports, more than the two weeks we recapped before it put together, and its stocks moved more of their implied move than in either of those weeks. On the typical ranked report, the options implied a 6.4% move and the actual move was 4.7%. A week earlier it was 5.8% implied and 3.1% actual.
Our implied volatility forecast did well in it. We graded 101 forecasts. The typical one missed by 4.3 points, 61 landed within 5 points, and on 72 of the 101 ours was closer than the simple guess anyone can make from a company’s past reports. Outside one day when volatility rose across the whole market, the average miss was 4.1 points.
Our richness reading had a harder week, with selling the straddle losing money in every richness group. The details are further down.
Our implied volatility forecast
Before each report we publish how far implied volatility, the rate options charge for movement, should collapse once the news is out. We grade every forecast at the close the day after and keep it on the record, hits and misses alike.
The closest this week was Merck: we said implied volatility would collapse 25.8%, and it collapsed 25.5%. Alphabet was next, 38.8% against 39.2% on its class A shares, then United Parcel Service, 38.8% against 38.4%. 26 of the 101 forecasts landed within 2 points and 61 within 5.
| Company | We said | It collapsed | Miss |
|---|---|---|---|
| Merck | 25.8% | 25.5% | 0.3 points |
| Alphabet | 38.8% | 39.2% | 0.4 points |
| United Parcel Service | 38.8% | 38.4% | 0.4 points |
| Cadence Design Systems | 21.1% | 21.6% | 0.5 points |
| JetBlue Airways | 19.6% | 38.6% | 19.0 points |
| Strategy | 10.0% | rose 10.3% | 20.3 points |
| Intel | 32.5% | 12.1% | 20.4 points |
Several of the week’s best-known names were close too. Microsoft collapsed 37.5% against our 36.0%, Visa 23.1% against 24.0%, Eli Lilly 37.4% against 38.3%, and Amazon 48.0% against 50.6%.
The forecast also held on stocks whose moves blew through their price. ServiceNow moved 23.7% on an implied 10.6%, and Fortinet 20.9% on 11.5%, yet both collapsed within 5 points of what we said: ServiceNow 36.8% against our 41.4%, Fortinet 46.2% against 48.8%. The forecast predicts what options will charge once the news is out, and on these two a move twice the size priced did not throw it off.
The simplest forecast anyone could make is that a company’s implied volatility collapses by its own past average, which takes nothing more than the free report history on each company’s page. That guess missed by 8.5 points on average this week. Ours missed by 5.4 and was closer on 72 of the 101 reports, in line with the 70% on the live record.
The forecast includes a correction for the way the textbook formula tends to overstate the collapse (how the forecast is made). We fitted it only on reports settled before October 1, so none of this week’s reports went into it. Without it, the textbook forecast would have missed by 8.4 points on average, with 39 of the 101 within 5 points.
The average miss of 5.4 points was a little wider than the live record’s 4.5, which includes this week. The misses leaned a little: on 59 of the 101, implied volatility collapsed less than we said, by 1.9 points on average, close to the record’s 1.4. JetBlue missed the other way: its implied volatility collapsed nearly twice as far as we said.
Why Intel and Strategy missed
The two widest misses were graded on the same day. On Friday October 30, implied volatility rose across the market. On options on funds tracking the S&P 500, the rate for the month ahead went from 13.1% to 16.0%. On the Nasdaq 100 it went from 21.0% to 25.1%, on a fund of chip stocks from 37.6% to 42.8%, and on a bitcoin fund from 35.7% to 40.0%.
The 28 reports graded that day missed by 8.5 points on average, and on 27 of them implied volatility collapsed less than we said. The guess from each company’s past reports did worse on the same 28, missing by 11.2. The other 73 reports of the week missed by 4.1 points on average and leaned slightly the other way, by 0.6.
Strategy holds bitcoin, and its options moved with the bitcoin fund’s: its rate for the month ahead went from 68.5% the day before to 76.1%, even with the report behind it. We said its implied volatility would collapse 10.0%; it rose 10.3%. Intel is a chip stock and was graded the same day. It had also just moved 29.3% against an implied 8.0%, the largest move of the week against its price. We said its implied volatility would collapse 32.5%; it collapsed 12.1%.
The forecast reads option prices the day before the report, so nothing in it could have seen October 30 coming. It does allow for the November 3 election, which fell inside the options we graded (they expired on November 6), and for the Fed’s rate decision on October 28. Both misses stay on the record as graded.
What the richness reading did
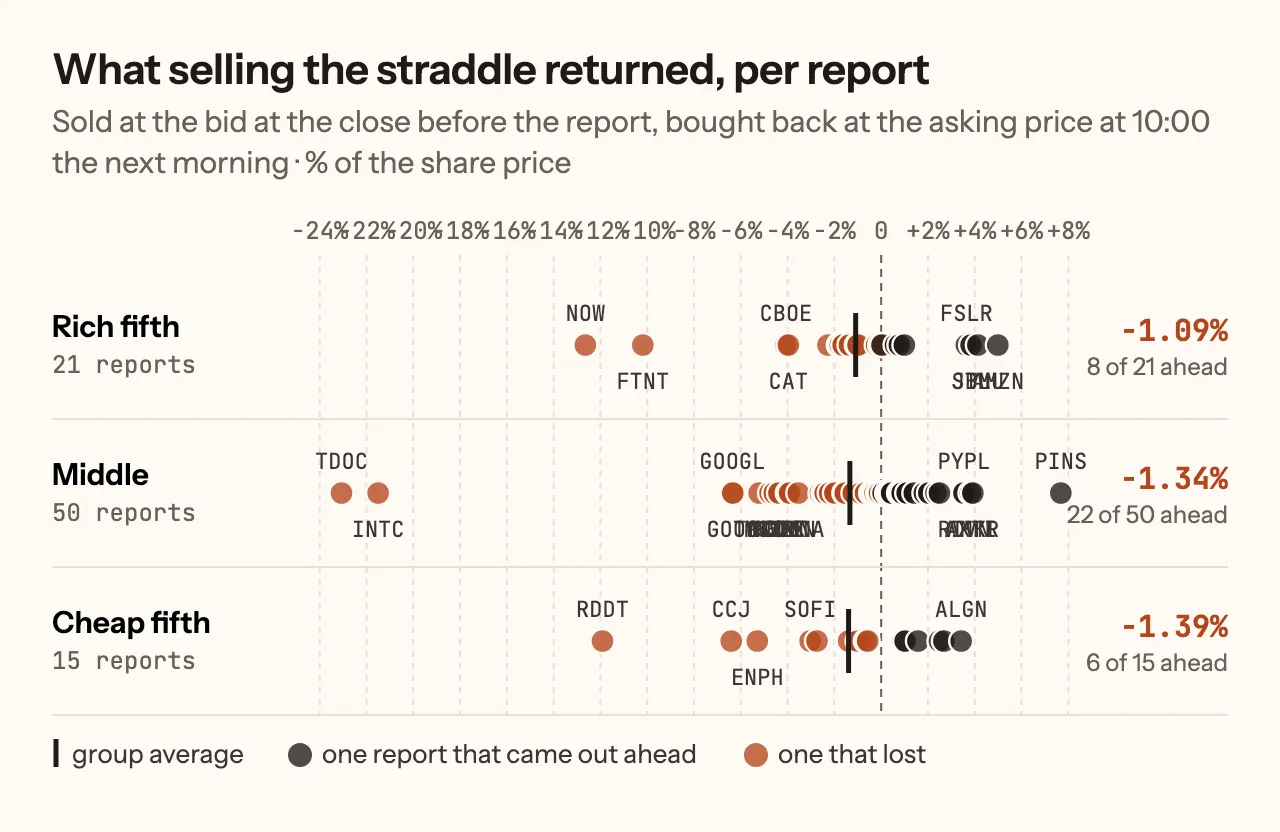
Before every earnings report, the board also gives the company a richness reading: how rich its options are compared with its own past reports. This week it did not separate the reports. Selling the straddle at the close before the report and buying it back at 10:00 the next morning lost money in every group. The rich fifth lost the least, 1.09% of the share price per report, against 1.34% in the middle and 1.39% in the cheap fifth, but gaps that small are well within what luck produces in one week. On the share of the implied move, the order did not hold either: the rich fifth’s typical stock moved 72% of what its options implied, the middle’s 62%, and the cheap fifth’s 65%.
| Group | Reports | Came out ahead | Average result |
|---|---|---|---|
| Rich fifth | 21 | 8 | −1.09% |
| Middle | 50 | 22 | −1.34% |
| Cheap fifth | 15 | 6 | −1.39% |
| All 86, no picking | 86 | 36 | −1.29% |
Two reports read 100, which means they were priced richer than every earlier report from the same company. JetBlue was priced for a 23.8% move and moved 14.1%, and the trade made 4.14%. Boston Scientific was priced for 8.3% and moved 8.4%, and lost 1.62%. The best result in the rich fifth was Amazon: reading 83, priced for 8.0%, moved 2.2%, and the trade made 4.99%. The worst was ServiceNow, also at 83, which cost a seller 12.64%.
How the reading works
Before a report, the price of a straddle (a call and a put at the same strike, the one nearest the share price) tells you how big a move the market is paying for. We call that the priced move, or the implied move. Part of it is the stock’s ordinary day-to-day movement, which it would have with or without the news. We strip that part out and compare what is left, the move priced for the report itself, with the same company’s own past reports.
The result is a percentile. A reading of 90 means this report is priced richer than 90% of the company’s earlier ones; a reading of 10 means it is cheaper than all but 10%. It compares a company with itself, never with other companies, and it says nothing about which way the stock will go. The board lists the richest readings first. The full definition is in the methodology.
512 of the week’s 757 reports had a reading. For 389 of them the nearest option expiry after the report was weeks away, and 35 more had option quotes too wide or too thin to trust, so the board leaves all of those unranked (more on them below). That leaves 88: 21 in the rich fifth, with readings of 80 or above, 52 in the middle, and 15 in the cheap fifth, at 20 or below.
What the stocks did
We measure the actual move from the close before the report to 10:00 the next morning, which is when a seller who buys back early sees it. 59 of the 88 ranked reports moved less than they were priced for. Here is each one against its priced move, richest reading at the top. Alphabet appears twice, once for each of its two classes of shares.
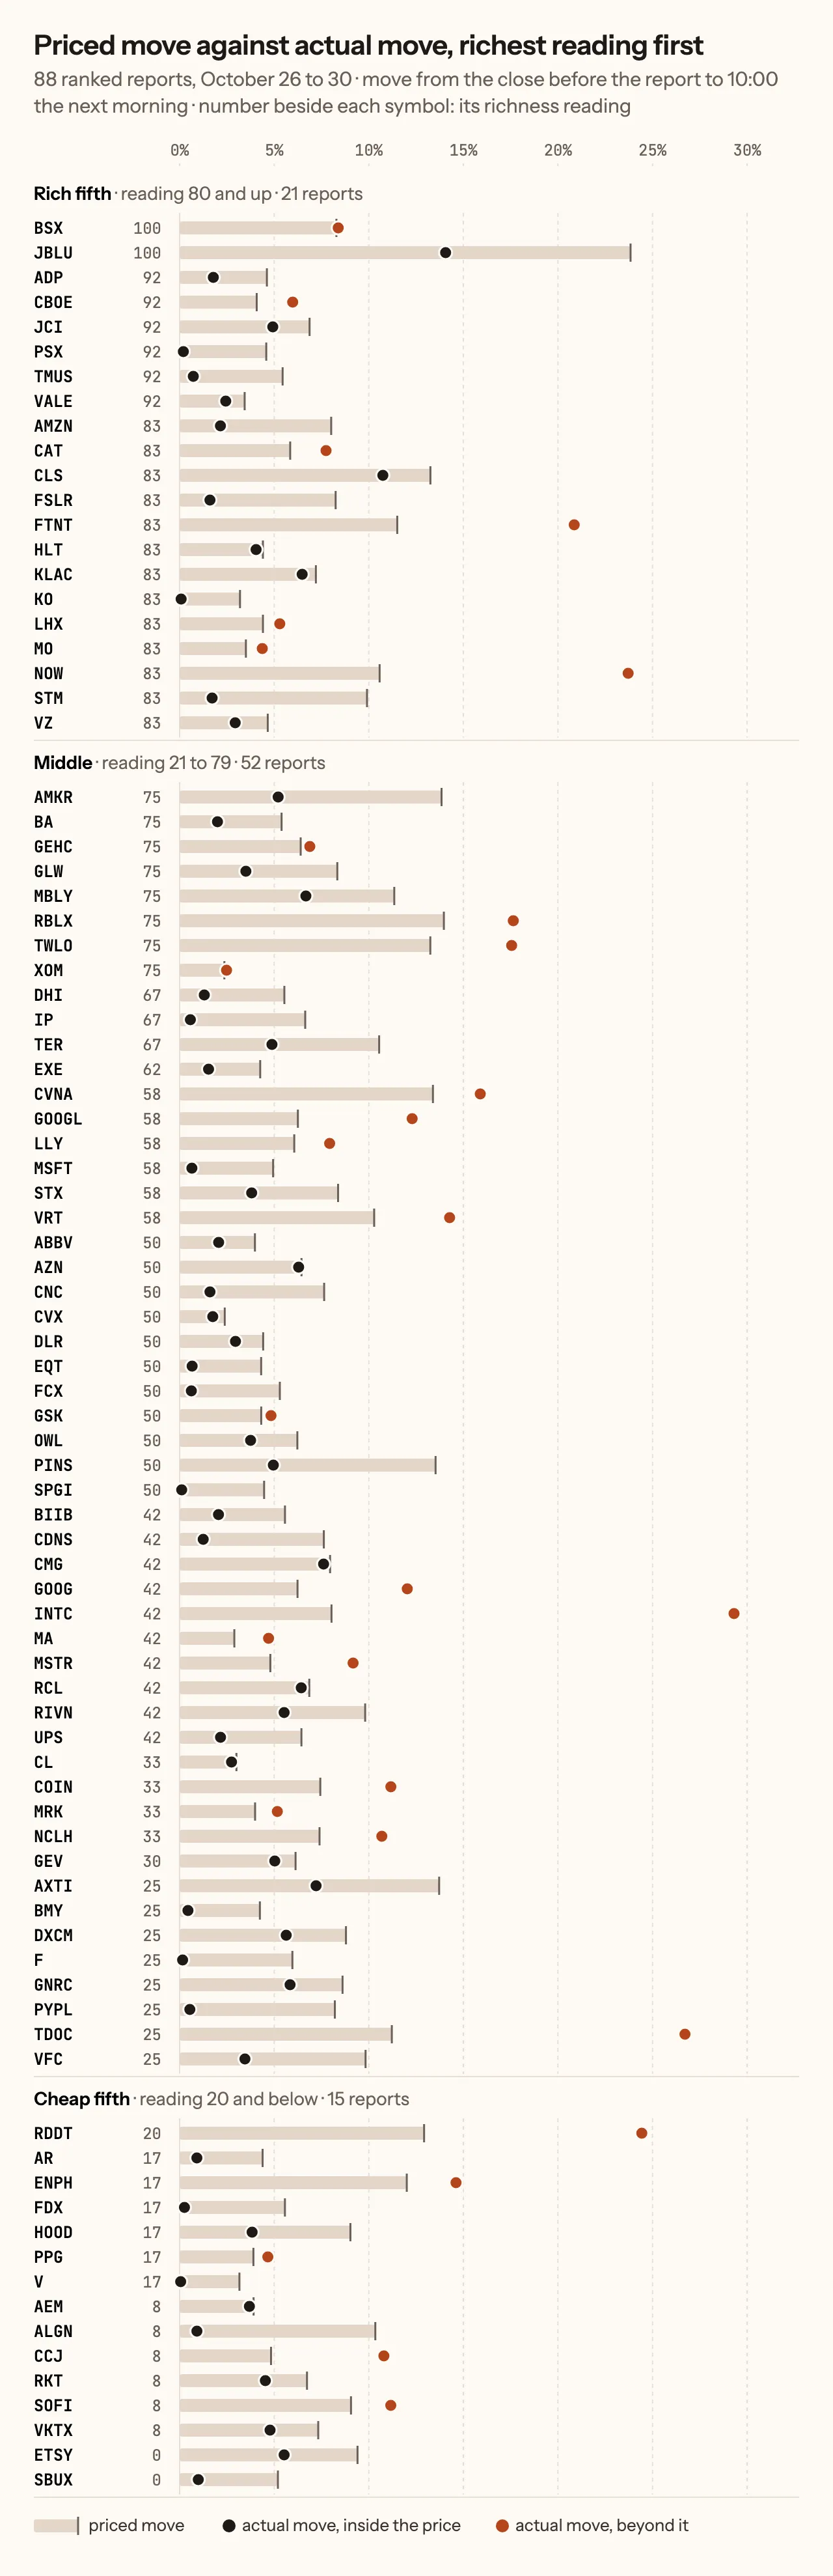
Seven of the 21 rich reports moved further than they were priced for, against 17 of 52 in the middle and five of 15 in the cheap fifth: about a third in each group. In the rich fifth they were large: ServiceNow moved 23.7% on a priced 10.6%, and Fortinet 20.9% on 11.5%. In the middle, Intel moved 29.3% on a priced 8.0%, and in the cheap fifth Reddit moved 24.4% on 12.9%.
For each report we priced the simplest trade the reading speaks to: sell the straddle at the bid at the close before the report, then buy it back at the asking price at 10:00 the next morning. Those are prices a seller could actually have traded at, so every result already pays the gap between bid and ask in both directions.
Why the board leaves some reports unranked
544 of the unranked reports could still be priced as a trade. At the halfway price between bid and ask, selling them came out about even: −0.09% of the share price on average. At prices a seller could actually have traded at, the same trades lost 7.94% per report. On the 86 ranked reports, the same two figures were −0.16% and −1.29%.
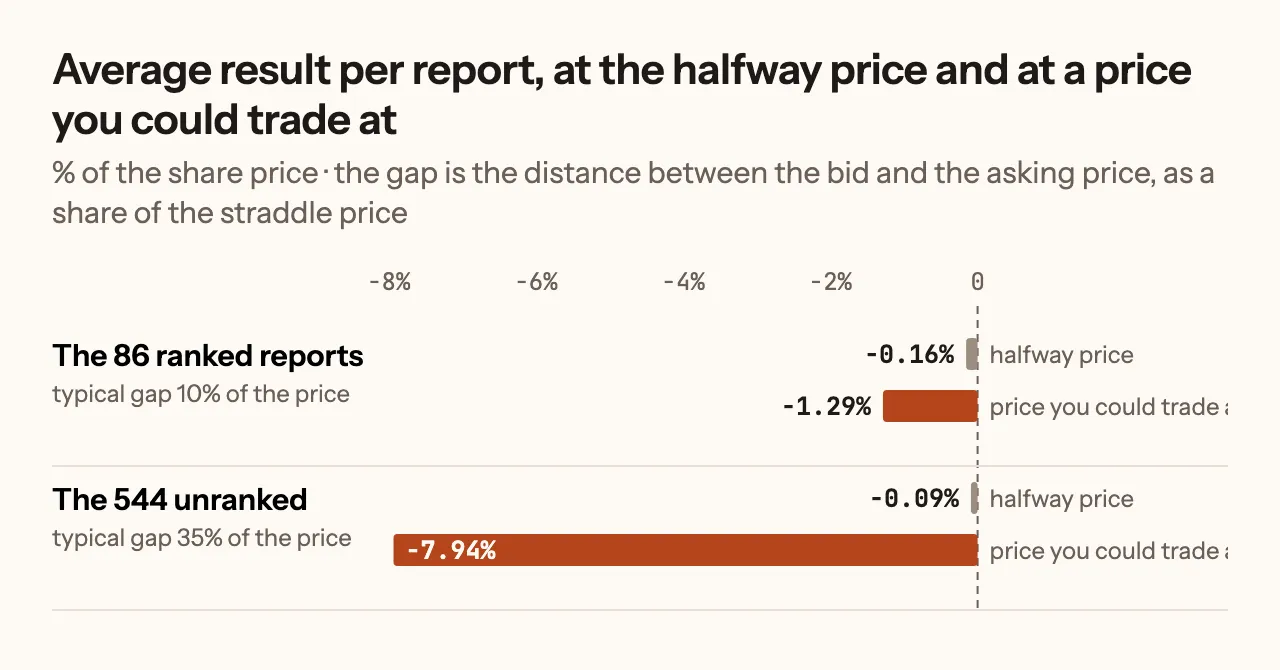
On these names the gap between bid and ask was typically 35% of the straddle’s price, against 10% on the ranked reports. Most of them had options that ran for weeks past the report, so the report was only a small part of what the straddle cost. A reading there would mostly measure ordinary movement, and the gap would take much of the premium before the stock moved at all, so the board shows none.
How much one week can tell you
The forecast’s week rests on 101 graded reports, and its result matches its longer record: about seven in ten closer than the guess. The richness reading’s rests on 86, and if you pick 21 of them at random, their average is as good as the rich fifth’s 44% of the time. So this week says almost nothing about the reading, in either direction.
Neither sample is as independent as its size suggests. Software and chip companies made several of the largest moves, and one market-wide day decided the forecast’s worst grades. One week cannot show how often a result repeats, which is why we keep the record beside these recaps.
Where the reading is
Every company reporting in the next 14 days is on the board, richest reading first, with a forecast and a reading for each one whose options give a clean one. A free account opens today’s rows; the rest of the fortnight is what a subscription adds.